 These days we are seeing how the moment of truth is slapping Eurozone politicians in the face. The risk premium, i.e. the market's disdain for Italian debt is throwing the country, and therefore the rest of the Eurozone, into bankruptcy. Watching the Italian giant teetering on debt feet worth more than 120% of its vast GDP, Greece's bankruptcy may seem like child's play. (more…)

 If I were a Greek and a businessman, it would be clear to me. My business would have a very dark future in the Eurozone with a wildly recessionary economy. With rising taxes aiming at desperate tax collection and consumption collapsing, my sales and chances of survival would be nil. And if my business had the capacity to export, I would also not be able to support it with a euro as expensive as the current one, as my competitiveness would be and will be at rock bottom in a foreign exchange environment that only German productivity will withstand.
 Today we’re bringing you a real gem in the form of an interview. It is none other than the one given by the best fund manager of the first decade of the 21st century, Bruce Berkowitz, to the prestigious financial journalist Consuelo Mack just seven days ago. It is fascinating to read Berkowitz’s arguments and convictions today, right in the midst of the financial storm, when his flagship fund, Fairholme, has lost almost a third of its value since the start of the year. A slump that many see as a sign of his decline as a fund manager, but which some view as a huge opportunity. His interviewer, Mack, is regarded by *Money Magazine* as «the best money TV host», and her programmes attract a huge audience. Enjoy Berkowitz’s reflections whilst the financial world crumbles around us (we’ll be posting the full Spanish translation shortly):
 Yes, but no. This seems to be the direction the EU is taking with its existential doubts. An uncertain course with the pretence of treading water, buying time, hoping that the Eurozone will still be able to breathe, when the sun wants to rise over a horizon that today is still black, very black.
 Let's make a very simple and brief emergency analysis of what happened in the markets and within the ECB last Thursday and Friday. As you have all seen, in unison with rumours of a Greek default, the Euro plummeted almost 3% to 1.3650 in less than 48 hours and almost 6% in 10 days. All indicators of Greek default risk were stressed, breaking all-time records. Risk premiums spread, of course, to the rest of the European periphery. Germany leaked the readiness of its bank rescue plan in the face of the imminent Greek default. And markets plunged another 4% across the board, spreading to Wall Street. Meanwhile, politicians continue to juggle grenades, and it seems that the only one lucid enough to realise the impending danger is Mr. Market.
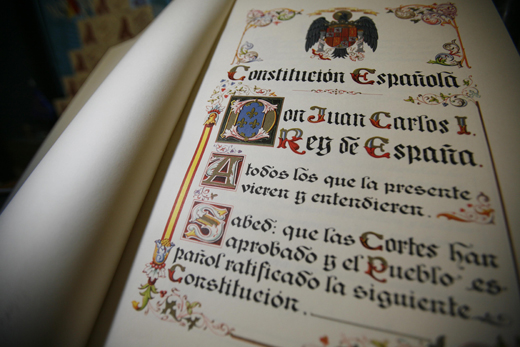 Much is being written about the constitutional reform that is supposedly intended to limit Spain’s public deficit in the coming years. We are all seeing daily statements denouncing that we have been sold out to the markets, that the Constitution has been amended under cover of darkness and with malicious intent, that it is unacceptable for the welfare state to be subordinated to the dictates of the markets, and so on. I would like to draw particular attention to the article published on 1 September in