By this time on Maundy Thursday, employees of Cypriot banks will have already received surreal instructions to open the bank branches after two weeks of being shut tight. The banks will be open to the public for six hours, during which time withdrawals of more than 300 euros will not be permitted, nor will it be possible to cash cheques or make international transfers exceeding 3,000 euros. Nor will it be possible to physically take money out of the country; in other words, the freeze even affects those who were forward-thinking enough to keep their money under the mattress.
.
For those considering selling off some of their assets in order to raise money and keep it out of the reach of European confiscation, a ‘corralito’ has also been imposed on property and exports. In other words, anyone selling land or property, or carrying out any kind of export of services or goods, is also obliged to deposit the proceeds of that transaction into the banking system. A one-week period has been set to assess how the imposed controls are working, which may be extended indefinitely.
.
It should be clear to everyone that these capital controls may soon see changes to their specific restrictions (amounts and types of transactions), but essentially they will remain in place for many months, perhaps beyond 2013. In other words, The free movement of capital will not be seen again in Cyprus for a loooong time, by which point the frozen money will be worth far less. That is the nature of ‘corralitos’: the purpose of the freeze is to strip value from the frozen assets. And this can be achieved either through an external devaluation of the currency (in which case Cyprus would leave the Eurozone and the assets would be converted into a new local currency), or through a direct confiscation of the money held by residents and non-residents (mostly Russians), as is the case here. You don’t freeze an entire country’s money just to beat about the bush; you freeze it so that the state or the banks can steal it, either partially or in full, one way or another, with the complicity or even at the behest of the Eurogroup and the European Commission in this instance.
.
For all these reasons, the real ‘corralito’ begins today, when the banks will reopen their doors whilst the Cypriot banking system remains closed. And this situation will continue until the government and the EU decide that they have plundered enough of the assets of the unsuspecting people who deposited their money in Cypriot banks. And the same can be said of what might happen at any moment on the periphery of the Eurozone, as soon as the markets become tense and sufficiently distrustful and the respective governments find themselves compelled (or not quite so compelled, in the case of the more left-wing ones) to take such action.
.
Another question that remains unanswered to this day is whether the confiscation will apply only to deposits and other funds recorded on the banks“ balance sheets (IPFs, structured products, junior and senior debt, the bank’s own shares, and other financial products of the institution), or whether assets held off-balance-sheet that have simply been deposited with Cypriot institutions (shares, external investment funds, etc.) will also be affected. Bank insolvency should not, legally speaking, affect assets outside the banks” balance sheets, for which Cypriot financial institutions act merely as custodians. But legal certainty is conspicuous by its absence throughout this process, and the Eurogroup has demonstrated and fostered a level of legal uncertainty across the entire Eurozone worthy of the worst banana republic. We shall therefore see in the coming hours whether not only assets that have entered the balance sheets of Cypriot banks are affected, but also any assets that have simply passed through the physical or electronic gateway of their banking system. The fact is that we are not dealing with a ‘mere’ bank default, but with a bank and sovereign default that attempts are being made to contain by neurobureaucrats and inept, Central European politicians.
.
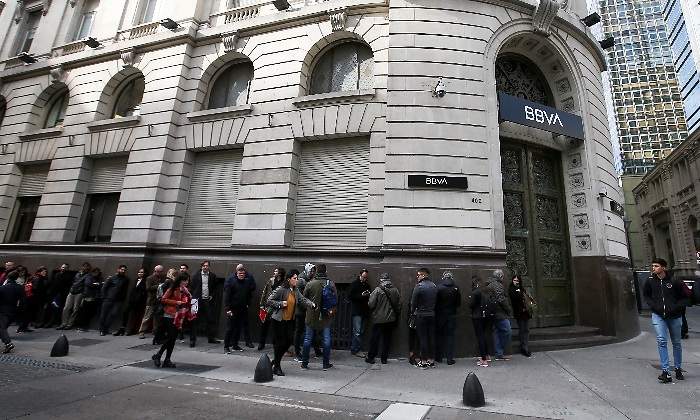
Speaking of incompetents, whilst a vague and contagious wave of panic begins to sweep across the Mediterranean, some leading Spanish banks are issuing desperate circulars to their customers in a bid to prevent a massive, legal exodus of capital abroad. In these circulars, we can read phrases worthy of a magistrates’ court, given their falsehood and malicious intent, such as:
.
With regard to the possibility that the same circumstances might arise in Spain [in Cyprus], at BBVA Private Banking we categorically reject this, now that the financial sector has been bailed out. Indeed, Spain now has a sound financial system, thanks to the FROB’s bailout of all financial institutions facing solvency problems, totalling 40,000 million euros. This bailout, together with the creation of SAREB (which has enabled nationalised banks to offload their problematic assets) and the two Royal Decrees that have required the entire Spanish financial system to make a significant provisioning effort, currently ensures a sound and well-capitalised banking sector. What is more, now that the financial system has been stabilised, keeping deposits in Spain is even safer than keeping them in many other European Union countries.
.
However, the Managing Director of the IMF, Christine Lagarde, warned just a couple of weeks ago the weakness of the Spanish banking sector, which is overexposed to Spanish sovereign debt and holds a disproportionate amount of property. Lagarde emphasised the high probability that both types of assets would lose value in the future, thereby creating a further need for the recapitalisation of the Spanish banking sector. And that’s without even considering the capital flight that the Cypriot ‘corralito’ might trigger – which would be like disconnecting a terminally ill patient from life support whilst simultaneously cutting their veins. Nor must we lose sight of the fact that, since the onset of this crisis, the IMF’s rhetoric has been politically correct and, as such, optimistic and unrealistic. That is why circulars such as BBVA’s are of a Kafkaesque moral depravity, prioritising the bank’s commercial interests over the financial security of the public. Once again, the Spanish banking sector is prioritising sales targets and the survival of the banking business over the most basic professional and personal ethics, but this time in an already extremely dire situation, which makes their actions particularly reprehensible.
.
As you can see, the situation into which the Cypriot ‘corralito’ is dragging us is a very delicate one for Spain and Italy. The masks have now come off, and people are finally speaking plainly. Bailouts will be paid for by the people who need to be bailed out. And if this means blocking, confiscating, restructuring, regulating and stealing from citizens, rest assured that the necessary measures will be taken to pseudo-legalise these actions, as is currently happening in Cyprus. The money needed will be found wherever it is and wherever there is enough of it. First, investors in banks; then their depositors; and perhaps all their customers – initially only at national level. That would probably be enough, but if it weren’t – because the shortfall were greater and/or too much money had already left the country – the next step would be to freeze overseas accounts held by citizens of the country in question. Is there life beyond this? There is, but unfortunately not for savers with less than €250,000. Just the management of our assets from banks abroad which are not owned by a Spanish legal entity It currently provides a sufficiently secure barrier against the confiscatory greed of countries in financial straits acting in collusion with Brussels. We are faced with a situation in which the aim is to use the money of others – who are more naive and less far-sighted – as a buffer between the confiscator and our assets. Let the money of others who are more trusting and/or have received poorer advice be the source that meets the capitalisation needs of banks and governments. Because when that happens, law and order (and, why not, economic growth) will return to normal, but along the way the assets of those members of the public who have taken fewer precautions will have been left behind. We face a long, mine-strewn desert in which surviving thirst and heat (the economic crisis) does not prevent us from dying simply for having stepped in the wrong place (confiscation and capital controls).
.
After all The EU will provide legal cover for any plundering that serves to keep the periphery afloat without affecting the pockets of the richest countries. Technically, the restrictions to be determined by the EC are referred to as “overriding reasons of public interest”, under which anything goes, such as: “…including bank holidays, limits on cash withdrawals, the freezing of assets, a ban on closing fixed-term deposits and on executing certain payment orders, restrictions on the use of credit, debit or prepaid cards and on other banking transactions, and on the execution of certain transactions subject to the Central Bank’s approval (note), as well as other measures…”. Solidarity is a thing of the past. All that remains now is the legal uncertainty imposed by the Eurozone mafia, and our own misery. The ‘corralito’ has only just begun.


 Tim Haywood is the chief investment officer and head of the fixed-income division at the asset management firm



 The rhyme is easy. But there is no animosity towards that nation, far from it, as what happened in Cyprus would be comparable to what has happened in the rest of the southern periphery of the Eurozone. The circumstances and the rhymes of a Greek, Italian, Spanish or Portuguese person are different, but the parallels are undeniable, and
