We look after your interests

(+34) 93 626 47 75

Torres Sarrià, Carrer de Can Ràbia, 3-5, 4ª Planta BCN 08017

(+34) 91 794 19 82

Pº de la Castellana, 93 2nd floor MADRID 28046

Cluster Family Office Blog

The Resilient Investor.

Let me start by saying that the observations I am about to make refer to an average investor with average capabilities and little preparation for the financial world – in other words, the majority of the population who have sufficient purchasing power to consider investing beyond simply making ends meet. Naturally, many readers will stand out from this average profile and should not feel that this applies to them. However, based on our experience with consultations of all kinds, we can confirm that what happens to the investors we are about to discuss is, unfortunately, all too common. We believe that by helping to identify the problems, we are taking steps towards resolving them or avoiding them in some way. Just as there is companies specialising in helping other companies become more resilient, it is also vital from the point of view of Counsellors that we can make the investor more resilient.
Many investors’ assets are subject to the sectoral cycles that their own salaries help to offset. These investors have a more or less fixed income from their employment, and on that economic basis take their first tentative steps into equities, investments in alternative energy, property, mixed financial products recommended by their fund managers, and so on. Most of them compulsively switch from one type of investment to another, depending on how things have gone for them. It is common to find people who, after a a year of misfortune After getting burned in the stock market, they spend a few years vehemently denouncing the vagaries of the markets. They usually swing from one extreme to the other, investing excessively in property or even in fixed-income products with an annual 3% yield. But everything passes, and the temptation to see how their friends have made a fortune five years later, in any equity fund, eventually erases from their memory the bitter words uttered by their financial advisor: «The correction is proving more severe than expected, but very good opportunities are now beginning to emerge; you should inject more capital to average down and capitalise on the falls…». Inevitably, just as they decided to cut their losses and change strategy, the stock markets began their spectacular recovery. Shortly afterwards, the bewildered but proud average investor (none of us likes to admit our faults and failures) will try to offload a pile of properties accumulated to the point of obsession and now overvalued, right in the midst of the sector’s slump. And not just for the sake of switching strategy towards the stock market and «stop messing about at 3%«, but because the mortgage commitments already entered into are becoming dangerously burdensome when property prices stop rising by 25% a year between the off-plan purchase and the handover of the keys.

The same applies to other investment strategies involving various financial products: when you lose out on oil, you move on to precious metals, preference shares, currency speculation, and so on. Even if we pick the right products and enjoy months of prosperity, our own fund managers and advisers (little angels…) will see to it that we switch from one to another depending on «the deal of the day» they need to sell. Investments in other people’s businesses can end up putting them «keep your leg on top so they can't get up«.

The result of these «strategies» investment strategy over the decades: a whimsical, disjointed, haphazard and, of course, expensive mishmash. A series of sharp turns in their investment strategy that will have nothing to do with their families« life goals. That «I've put my foot in it; I'm off there to make amends«...it won’t end in tragedy if they at least have some paid-off property left over from their time in the property market.”.

Some of you might think we’re over-dramatising things, since if, come our old age, we still have a property or two and a few other assets, it will mean we haven’t done too badly after all, despite our erratic path. Here I must disagree, because we must bear in mind what we said at the start of this post: the ability to generate income from our work throughout our lives. The income we are able to generate throughout our working lives, the passage of time and compound interest work wonders. If we take all this income – obviously after deducting our family’s expenses – the surplus generated by even very moderate compound interest would surprise more than a few people. Many families would probably have even more assets than they have accumulated after cyclically risking, gaining and losing their surpluses in various investments and businesses.

What we mean by this is simply that many adventures For the majority of investors, their investments would end in disaster if they did not have a surplus from their employment to help them, from time to time, mitigate the losses they suffer on the stock market, in business, with financial products and—though some may still not believe it—in property ventures too. If we were to strictly separate our earned income from our investment portfolio, we would see that only those investments made with a certain degree of judgement and rigour are self-sustaining. The rest, at one point or another in our lives, usually require an injection of funds from our salaries or inheritances. This false resilience (in the psychological sense of the term) stems from the regenerative capacity of the income derived from the investors’ own work. If we separate this earned income from our investment portfolio, it will likely become clear that our ability to bounce back after an investment setback is not what it seems. Many investors are not truly resilient without the support of their salaries; therefore, they need independent financial advice or a radical change of strategy, for the sake of their families’ future. In many cases, one’s earning capacity must bear the brunt of an individual’s investment errors and failures, minimising them to the point of distorting our view of our own wealth-creation capabilities outside of our work.

If we maintain this strict separation between our two economies, our investment ventures should be financed through loans. Thus, «inevitably»The investment itself should be able to pay for itself, clearly demonstrating our ability to make sound investments throughout our lives. An old friend used to say: «If a business can't even cover the interest on its bank loan, what a rubbish business.»We could then set aside the surplus from our professional income and reinvest it in fixed income, as we would already be assuming the risks associated with other types of investment independently. In this way, we would create genuine, fully protected savings plans for our later years, whilst remaining aware of our limitations and capabilities when it comes to investing.

As for the ability to create wealth, I would add:

«We’re all capable of making sound investments; we just need to seek advice from someone who can help us avoid making a lot of bad ones’.»

If we manage to do that, we will have achieved the status of Resilient Investor, in one of its meanings referring to the ability to thrive in an unhealthy environment. An interesting concept, don’t you think?

Crowdsourcing and self-managed VR portfolios.

The globalisation, the internet, the speed of information, the widespread availability of higher education, the instant exchange of knowledge and experiences across the globe, and investment opportunities globalised, etc. We could link all these concepts to the crowdsourcing and the love-hate relationship between retail investors and the equity market.
Just a few years ago, only a handful of investors dared to put their money into the stock market by making their own decisions. And those who did so had to be part of a elite from businessmen which operated with average volumes through brokers employed in large specialist firms which, paternally, they were responsible for recommending as many portfolio changes as possible with vampiric intentions. Small investors had to either sit on the sidelines or settle for whatever their bank could do with their savings – in other words, mediocrity or even inaction.

Nowadays, any small-scale saver with an interest in the stock market trades via the internet paying much lower commissions and with no one trying to sell them the catch of the day. This might lead us to think that it is detrimental to anyone who isn’t an expert in the field, but there are more benefits than drawbacks. Anyone looking for advice, information and opinions can find them in a host of traditional publications, but above all in websites and financial blogs. I should point out here that seeking advice from CincoDías o Expansion For example, it does not necessarily offer a better chance of success than reading a variety of other blogs. Both traditional financial channels and those that are more diverse but have a smaller readership can provide guidance excellent and also aberrant. In short, just like real life.


This form self-taught and free to learn, gather information and get misled wherever you like, so you can invest through whatever channel you choose in whatever you please is a crowdsourcing fascinating. The same potential investor who receives information, education and misinformation from any source or channel soon becomes a source of their own experience. They, in turn, disseminate information, education and misinformation just like everyone else, thereby expanding the range of options available at their fingertips click any other potential investor, who will be emboldened by reading about the experiences of inexperienced investors with whom they feel a sense of identification and support, encouraging them to enter the market.

Some might say it’s dangerous and reckless. That one shouldn’t try to be self-taught and that you should always go through an «expert» when investing in the stock market. Someone who knows a lot and tells you where you’ll make money and where you’ll lose it, in exchange for a share of your profits and losses, of course. Although, come to think of it, if they knew where you’d make money and where you’d lose it, they wouldn’t waste their time advising others in exchange for a measly commission.

As I’ve already said, I personally believe that the benefits outweigh the drawbacks. The crowdsourcing It can work very well for some stock market investors, and I think it’s a growing trend of which we should all be proud. The internet has done more for global freedom than many significant historical events.

Tools such as ETFs help to promote the independence of crowdsourcing and free small investors from the shackles of expensive financial products that rely on fund managers. This is similar to what happens with Savings.com o Selftrade For example. In short, there is a proliferation of tools enabling small investors to access stock market knowledge and invest their money however they wish, with ease.

The ethical aspect of all this, or the effects it has crowdsourcing Global investment in equity markets is a much more complex matter to analyse. Some may consider that the gambling addiction in the manner of my bid.com, others might call it finance for the masses. Like everything else in this world, it’s a matter of opinion. Perhaps it’s down to my almost pathological philanthropy, but I see it as a positive thing that small investors are gaining greater freedom, even if many of them lose money.

Strategic and wealth planning is a completely different matter. A PGR is a haute couture garment that must be crafted in collaboration with Counsellors honest and highly knowledgeable in their field. Dressed so elegantly and under their watchful gaze, let’s enjoy the best Crowdsourcing.

Does our economy need immigration?

Let me make it clear from the outset that this post is intended merely as a brief note offering a couple of reflections on a subject as complex as immigration and its effects on our economy. This flow out of control It is a fact, and what is more, the growth figures are rising just as dramatically as China’s economic figures themselves. In my view, immigration is simply another form of global distribution of wealth which takes place involuntarily, whether we in the developed world like it or not. Nor do we seek to judge the merits or demerits of the current flow of migration, which, in any case, is inevitable.
Poor people flee their countries to to benefit the standard of living found elsewhere on the planet. So far, this is understandable and, moreover, difficult to control given the globalisation which also applies in terms of demographics. If, moreover, the arrival of this population were to benefit theThe developed economy would close a effect cluster positive synergies. In other words, it is not just a matter of would tend to to bridge the economic gaps between countries, through cash flows which always flow from rich countries to poor countries in the form of wages sent to families who have stayed behind in origin, but there are also those who put forward the theory that the influx of cheap labour helps the First World to grow. Indeed, many politically correct economists would have us believe that, thanks to this influx of people from the Third World, our social security contribution system is able to generate sufficient revenue, and that low-paid jobs which locals would not want to do are being filled, and so on.

Personally, I see things differently and, in all modesty, I tend to agree more with the Doctor of Economics from the University of Harvard Xavier Sala i Martín. According to this eminent scholar of our time, the mass influx of cheap labour into the developed world gives rise to a range of strictly economic problems, including a slowdown in technological progress. Without going any further, many Spanish local authorities prefer to re-hire teams of immigrants to sweep the streets rather than continue to purchase specialised vehicles that carry out this work of sweeping and cleaning drains, kerbs and pavements in urban areas. It is significantly cheaper to hire teams of street sweepers, who need only be provided with a basic broom and a meagre wage, than to fund vehicles ultra-modern that can carry out the same work with just one qualified operator. We are undoubtedly facing a dangerous technological regression which, in turn, reduces the turnover of companies such as the one in the example that markets these vehicles and thus slows down their R&D. We could find a multitude of cases and diverse sectors where technological progress is regressing, leading to a return to employing human labour at wages that barely allow people to scrape by, crammed into substandard flats. However, what is unacceptable in our eyes represents an improvement in living conditions compared to those from which they fled in origin and which enables them to send essential aid to their families.

There are those who He argues that the local population would not want to fill low-paid jobs and that these would remain unfilled, leading to a lack of reliability in certain community services. A gross error. Quite simply, employers or the State would be forced to increase these wages until such jobs became attractive to the local population. As always, the efficiency of the supply and demand market would regulate our day-to-day reality. What is clear is that jobs would not remain vacant; rather, pay would simply be adjusted appropriately to the standard of living in our society.

As for the benefit to our National Insurance fund from immigrants’ contributions, it is highly likely that, in the medium term, this will result in a deficit when compared with the healthcare costs incurred by this section of the population.

We could consider other non-economic factors, such as the drastic decline in the average academic standard of our state schools due to the enrolment of children with serious language difficulties and/or who had never previously attended school. Or that the financial hardship faced by a section of this immigrant population inevitably leads them to to commit a crime, leading to a rise in public insecurity in countries receiving higher levels of immigration. However, these would be social rather than strictly economic drawbacks.

I would not want this post to come across as xenophobic or racist in any way, or even classist, as nothing could be further from my nature. In fact, I consider whAnd if we analyse the issue of poverty from a global perspective, it is not only fair for rich countries to curb their growth for the benefit of Third World countries, but it is also an act of solidarity and an ethical necessity. A significant reduction in the West’s wealth, in the form of wealth redistribution to the Third World, would, at the very least, be fair, although I suspect it might be dangerous for global growth. However, if we analyse the situation from a self-interested perspective, looking solely to the interests of the Western world, mass immigration is clearly detrimental to maintaining the current levels of well-being and economic growth.

We are talking about facts that political correctness seeks to distort by glossing over the negative effects of immigration on the economic systems of developed countries. Perhaps this is because immigrants are potential voters, or perhaps it is simply because trying to go against this trend is like putting gates on a field.

But the economic facts and figures support the arguments put forward by the eminent Xavier Sala i Martín. The author of Economic Growth is not only an economic expert at the University of Columbia, right in the very heart of Manhattan, where he teaches some of his classes, but he is also thoroughly familiar with the problems facing the Third World. It is no surprise, then, that he is the founder and director of the Foundation Umbele, with an exemplary administrative structure. I would like to take this opportunity to express my admiration for his professional and philanthropic career.


If we are able to adopt a more global and compassionate view of the world economy, we will not feel so threatened by the massive rise in immigration or by the collateral damage it causes. But I recognise that this is no easy task, and I must admit that my primary-school-aged children go to a private school.

Warren Buffett at his best. Lessons for rich and poor alike.

Warren Buffett, a role model for many in almost every respect, spoke at his latest Berkshire Hathaway Annual Meeting about what I would call the state of the nation. This meeting has become show which was one of the largest of its kind, attracting more than 27,000 people, and at which a wide range of topics were discussed, such as: Results for the first quarter of 2007, general comments on Berkshire Hathaway, comments on financial companies and risks within the financial system, comments on economic and business matters, investment advice, life advice and more. In each of these sections, topics as interesting as they were diverse were explored, with the depth afforded by an event of this scale and with the good humour instilled by its key figures, ensuring that a corporate meeting was regularly punctuated by bursts of laughter from the audience throughout the show. What better way to review the progress of an exemplary empire each year than by enjoying what, elsewhere, would be a soporific session of figures, ties and impersonal hair gel?
I would like to highlight what Mr Buffett said regarding his massive donation of 85% of his fortune:

Buffett: I always felt I would grow my money at a rate higher than average, and it would have been foolish to give away a significant portion of my capital, which would have been spent within months. I thought my wife would be the one to do it [give my fortune away], but that didn’t work out.

When my wife and I had a baby, we hired an obstetrician – I didn’t try to do it myself. When I have a toothache, I don’t turn to Charlie. Similarly, when it comes to giving money away sensibly, I let people who are smart, energetic and passionate do it. I want to hand over the reins to someone who can broadly follow the approach I would take if I were to do it myself.

As for the smaller grant applications, I pass them on to my sister Doris, who enjoys dealing with them.

As far as I’m concerned, I haven’t given up anything. Someone who gives up a night out or a lot of time or a trip to Disneyland because they’ve donated to a church or whatever – they’ve given something up. I haven’t changed my life. I can’t eat any better or sleep any better, so I haven’t really given up anything.

As I mentioned at the start, he’s a model of excellence. An all-powerful man who delegates to specialists of all kinds so that they can carry out his wishes in the most professional manner. Let’s not forget that we’re talking about a figure self-made of a generation of businessmen who grew up without following the academic paths taken by today’s generations: MBAs, postgraduate courses of all kinds, etc. Their ability to delegate is all the more commendable.

Munger: We have no system for estimating the correct value of all businesses. We put almost all of them in the “too hard” pile and sift through a few easy ones.

Buffett: We know how to recognise and step over one-foot bars, and recognise and avoid seven-foot bars.

The humility of one of the most powerful men on the planet is truly admirable. His ability to recognise the risks he can take has made him great.

Munger: When you’re trying to determine intrinsic value and margin of safety, there’s no single, straightforward method that can simply be applied mechanically by a computer to make someone who just presses the buttons rich. You have to apply a wide range of models. I don’t think you can become a great investor overnight, any more than you can become a bone-tumour pathologist overnight.

Buffett: Let’s say you decide you want to buy a farm and you work out that you can make $70 per acre as the owner. How much will you pay [per acre for that farm]? Do you assume that farming will improve, so you can increase yields? Do you assume that prices will rise? You might decide you want a 7% return, so you’d pay $1,000 per acre. If it’s for sale at $800, you’ll buy it, but if it’s at $1,200, you won’t.

Buffett: If you’re going to buy a farm, you’d say, “I bought it to earn $X by growing soya beans.” It wouldn’t be based on what you saw on the telly or what a friend said. It’s the same with shares. Get out a notepad and say, “If I’m going to buy GM at $30, it has 600 million shares, so I’m paying $18 billion,” and answer the question: why? If you can’t answer that, you’re not putting it through business tests.

The simplicity of the analysis is clear; what is truly difficult is applying it rigorously when it comes to putting our money at risk and managing our hopes and fears regarding a particular investment. When we carry out tests on paper, without actually risking our assets, things change; everything becomes clearer and easier. But as the master Buffett said at this very meeting:

I think you should read as much as you can. In my case, by the age of 10, I’d read every book in the Omaha public library on investing – some of them twice. You need to fill your mind with a range of competing ideas and decide which ones make sense. Then you have to take the plunge – take a small amount of money and give it a go yourself. Investing on paper is like reading a romance novel as opposed to actually doing something else (laughs). You’ll soon find out whether you like it. The sooner you start, the better.

At this point, I must say that I consider this advice to be beyond the capabilities of the majority of the population. Mainly because there are very few Warren in this world, but also because when he took the plunge with his modest sum of money, the market landscape was very different and infinitely less speculative. But it is only natural that he should continue to explain the system that led him to success, although that does not mean it is necessarily applicable to our present circumstances or to ourselves.

Buffett is exemplary in the method he has pioneered, in the preservation and steady growth of his fortune and, in my view, what truly makes him great: his donation of 37,400 million $. Of this, 31,000 million $ has gone to the Bill & Melinda Gates Foundation and 6,400 million $ to various organisations. He also frequently mentions that he hopes his donation will inspire other major fortunes to do the same, explicitly naming John D. Rockefeller Senior amongst them. If his example were to spread amongst the world’s great generational fortunes, we would be witnessing the most efficient distribution of global wealth. In short, an example of how to become rich, but above all an example of how to give meaning to the lives of the wealthy.

The Global Economy and Chaos Theory. Boring philosophy for those hoping for profitable formulas.

It is inherent in the human race to constantly strive to to foresee and take control of the future, and even more so when it comes to anticipating economic trends that could benefit our pockets homo erectus.
In today’s globally interconnected financial system, where efficiency is a constant guaranteed by the system itself globalisation, countless studies, theories, methods and complex mathematical formulas have emerged to systematise investment strategies designed to make us rich. This phenomenon also goes in crescendo, as well as their widespread adoption. These days, any reasonably experienced retail investor is keen to learn a few techniques that will enable them to outperform the average investor, in the belief that their returns will grow proportionally. Furthermore, the professionals who sell them access to these investments have adapted their approach to meet this demand from their clients. The «spend it on that You. »the same« or the »guide to making money in finance’, and it seems to be universally accepted that a better-prepared investor will achieve better returns than one who is not. Apparently, learning the necessary investment techniques is the path to wealth. But apart from most honourable major cases gurus in finance, that is not the case. And in those rare exceptions, investment technique is not everything; I would add that it does not even constitute a significant part of the tools used by those successful investors gurus.

It is not enough simply to have a good understanding of technical analysis or to be a fundamentalist expert. Nor are mathematical models capable of predicting market movements with sufficient certainty of success, not even Fibonacci or fractals. That would be far too easy. Geopolitical crises, international relations, the fundamentalisms Religious factors, technical advances in energy, genetic engineering, nationalist strategies, endless speculation of all kinds and, ultimately, a myriad of variables influence the evolution of the global economic and financial system. Some would say that the secret lies in combining all these tools to weigh up every possible variable. Undoubtedly, when used in exactly the right measure and with the timing If done correctly, they can form a relatively successful team, but we must not forget that we are talking about a system with infinite variables, where, moreover, the initial analysis can only ever be an approximation. Furthermore, the number of variables is constantly increasing; for example, speculation in today’s markets exceeds overwhelmingly that which existed during the ‘golden years’ of growth, when many of those who are now regarded as gurus laid the foundations for their personal financial growth. Consequently, their methods are no longer as useful as they were for their creators, as the current landscape involves very different variables. Constant change in the landscape, a variable unpredictable more.

It is much easier to forecast the weather for the next 48 or 72 hours. Although perhaps the system economic-The global financial system is indeed comparable to a weather forecasting system when we try to predict the weather more than 10 days in advance. In short, we could describe it as a chaotic system – that is to say, neither stable nor unstable.

If we conclude that our global financial system is affected by the notorious butterfly effect Inherent in human activity itself – precisely because it is a chaotic system – can we deduce the underlying order concealed by seemingly random phenomena? In theory, yes. The laws governing human behaviour mean that this system is deterministic, sensitive to initial conditions and with attractors (market laws). I do not know whether anyone has ever rigorously applied the precise mathematical formulas used to study chaos to the prediction of markets within the global economic system. Obviously, attempts have been made, but I fear they are nothing more than shots in the dark. Perhaps the leading exponent of Hurst, the eldest of Lyapunov or the relative complexity of Lempel-Ziv and the entropy Computer science, used to gauge the degree of disorder in data, might shed some light on the outlook for the global economy. Or perhaps not. But even if that were the case, perhaps this light shed on our financial chaos would not help us become rich either, since, unfortunately, our wealth is meaningless in an environment of widespread global opulence – at least, I cannot conceive of it being so. I am convinced that if, one day, a method of analysis were developed that was powerful enough to to foresee economic trends; market efficiency would continue to struggle against the predictable chaos.
I can’t help but smile when I see investors who have blind faith in their trusted «specialists», with whom they forge bonds of reverence that extend even to their most private assets, and who have no hesitation in recommending them to their friends as the philosopher’s stone of their finances. It is true that during periods when the markets behave in accordance with a limited number of variables eligible because of these experts, they make profits in excess of benchmarks, but all it takes is for chaos to sneeze for pneumonia to take hold of the assets of those managers’ clients. It is only a matter of time before the damage caused by variables not factored in by the investor becomes apparent, as the assets we have available for investment are more than finite. To give you an idea, something similar to what causes the popular martingale Like roulette, but with far more variables.

Even so, we can still aim to make financial progress with our investments throughout our lives, although there are, of course, no guarantees of success: a strategy tailored to our personal needs, all the technical tools at our disposal, taking into account as many variables as possible, and exemplary risk management (I recommend reading Rebuzner), prudence and a great deal of humility. If, moreover, we are able to adapt all of the above to the current global situation at every turn, we will simply be at the mercy of the imponderables, Chaos, or what is also known as chance. Or perhaps we call ‘chance’ that which we are not yet able to foresee, but which is intrinsically foreseeable?

Unfortunately, the average investor will continue to place their trust in fund managers men in suits and ties which they operate indecipherable tools that will make them rich (sic), but who remain in their jobs, trying to minimise their failures as much as possible, even at the expense of their own personal assets. Sometimes they even succeed, and merely go bankrupt periodically alongside their clients. Success will be achieved by those whose life cycle is not long enough for a crisis to, crack or some unforeseeable factor fatally undermines his winning strategy within the System. Despite everything, who said anything about fear? The dollar-euro exchange rate at 1.65, bearish stock market cycles as soon as these levels are reached, rallies generalised interest rates, yuan through the roof…. rien ne va plus. We’ll always have Chaos to cling to.

The culture of the ‘Pelotazo’ and ‘Pixie Dust’.

A considerable number of people in this country – I would go so far as to say the majority – spend their most productive years waiting for the opportunity to carry out the big score of their lives. Some even aspire to achieve more than one. Why would it be difficult when they see all sorts of examples around them every day? So they choose to drift through their jobs, on the lookout for some one-off, truly spectacular investment that will lift them out of mediocrity and catapult them straight into opulence. Or worse still, they hope for a series of smaller-scale investments, repeated often enough to achieve the same result. Why go to all that trouble of setting up their own business or trying to get ahead in their jobs for the sake of a mere promotion which, as well as bringing greater responsibility, will only allow them, in the short term, to go on an all-inclusive holiday just a few minutes’ flight away?
However, although it may seem strange to many, in other parts of the world the middle class has been aspiring to move into the upper-middle class for several decades. They aim to own a stable business or to work hard and productively as employees in order to climb the career ladder within various companies (or the same one) with slightly better conditions. Thus, with a bit of well-deserved luck, they are likely to reach their forties with sufficient savings to make ends meet without any surprises, and a private retirement plan consistent with their career trajectory throughout their lives. Of course, this requires a certain level of ability and considerable sacrifice, which is eased if one manages to enjoy what one does. Achieving a decent level of financial independence by retirement age is the ultimate goal of their progression throughout their working lives. For example, in the US there are large companies specialising in organising the best possible retirement for executives and employees of a certain age and seniority.

It may seem like an unattainable prospect to a few, but it is not for the majority of the middle class with average abilities. Many others may find this a bleak, mediocre or unambitious outlook on life, but let us remember that we are referring to the future prospects of the majority of our middle-working class with medium-to-high aspirations. I sincerely believe that, for all of them, aspiring to financial security in retirement is neither sad nor unambitious, but rather a success for which one must work hard throughout one’s life. Not forgetting that we must enjoy the journey, of course, but unfortunately life is just that difficult for most of us, although for some it is obviously even harder.

Interestingly, in Spain there are many young people who have other plans for their financial future: to become rich before the age of 35 or 40. Is it possible? Of course it is, but it’s also unlikely. That’s why, if we devote our most productive years – say, between the ages of 25 and 40 – solely to chasing the chance to get rich, whilst neglecting our gradual progress, we’re leaving our future in the hands of an opportunity that will probably never come. And even if it does, we probably won’t be able to recognise it. As long as we spend our lives waiting for that windfall Our progress will be flat at best, as our hopes and energies will not be focused on our day-to-day work or profession. Making gradual progress in our careers does not mean ignoring any opportunities that may arise, but rather preparing for the long-term future in case that golden opportunity never materialises, as the laws of probability would have it.But there are those who prefer to spend their youth and early adulthood in low gear, daydreaming about fairy tales and turning their backs on opportunities to get ahead at work, however small. Merely waiting for the end of the working day, the arrival of the holidays and a less demanding job with fewer responsibilities – and, as a result, probably one that is less productive. With more free time to spend money they don’t have and constantly lament this fact. This not only leads them to the systematic ruin but also to the chronic unhappiness. Complaining about injustice is often impractical. Perhaps this alarmingly widespread behaviour in our society is also linked in some way to Peter Pan syndrome, albeit exacerbated by constant encouragement to consume.

However, dreaming of fairy tales like those in Disneyland It is very encouraging if you have a clear understanding of the chances of success and what each of the ingredients in Mr Walter Disney’s ‘magic formula’ for making dreams come true consists of: «Faith, Trust & Pixie Dust». Having faith in our potential and believing in what we are doing are logical principles that nobody should overlook. But to stand any chance of making our financial or career dreams a reality, the pixie dust It won’t fall from the sky or be brought to us by Tinker Bell; we must contribute it ourselves in the form of dedication, hard work, intelligence, ability and, ultimately, all the virtues necessary – though not sufficient – for success. Unlike in fairy tales, the ‘pixie dust’ of Peter Pan and his faithful friend Tinker Bell will have to be created through our own efforts. Only then does the formula stand a chance – though no guarantee – of success. For all these reasons, and above all because of the uncertainty of the outcome, the crucial thing will be to enjoy the journey – that is, the gradual improvements in our working lives that we will achieve over the decades. We can find happiness for our loved ones in various ways, but perhaps the one most consistent with the economic reality we live in is to find it in the well-being and security achieved over time. If we separate our happiness from work, it will be very difficult to attain it. Unfortunately, our society is based on work and production; therefore, being happy apart from that is an almost impossible task. Furthermore, unhappiness at work makes economic progress more difficult for us, thus creating a cluster effect negative.

The pursuit of a get-rich-quick scheme not only leads us astray from the path of steady progress but also seriously jeopardises our precarious current stability, as betting on such a scheme usually involves investing money one does not have, whilst taking reckless risks. If it goes well the first time, it’s only a matter of time before poor risk management eventually sets things right in the medium term. In a scenario where, in all likelihood, we’ll never land that dream windfall, and where the state won’t be able to fund our pensions, what alternatives do we have if we don’t want to live on the fringes of the system? Let’s give free rein to our imagination – I look forward to your comments.

Create your own future

»It will be as small as the desire that controls it, as great as the aspiration that dominates it» – James Allen.
It seems that we become what we think about most of the time, and what do leaders think about? The future, where they’re heading, and what they can do to get there.

Everyone else is preoccupied with the present or the past, with the pleasures and problems of the moment – things that can no longer be changed.

For effective personal strategic planning, we need to start by developing a long-term vision for our lives. Hence the importance of dreaming, of imagining what our future will be like, and of what we will do to achieve it.
But of course, to get anywhere, we first need to know where we want to go and set ourselves goals – whilst always staying true to ourselves and to what we enjoy – because, after all, happiness lies in the journey itself.

Taking action, getting started and keeping going is, perhaps, the hardest part. You have to be persistent. However, to achieve a different result from those obtained so far, you have to take different actions. The daily grind, personal commitments, tiredness… all of these things prevent us from starting what we know we need to do to achieve those dreams and, of course, from sticking to our goals.

To be persevering, you need to be motivated. The question is: how can you avoid giving up in the face of problems and keep moving forward? Without ever losing sight of the outcome we’re hoping for – the one that makes it all worthwhile to keep fighting. But that’s easier said than done; it’s something each of us must find within ourselves.

The Ferrari, diesel. Orange juice, natural. And the Euribor, +0.30.

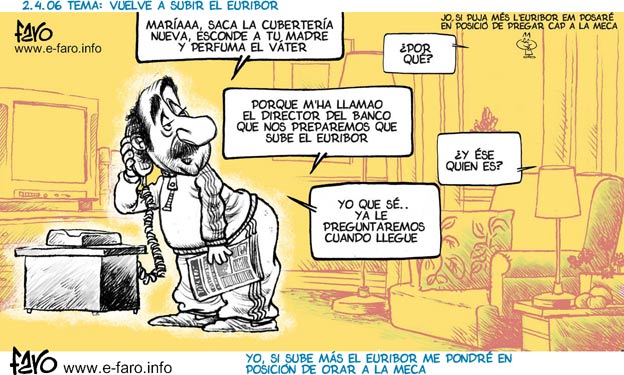
Yesterday I read the comments of an executive at a financial institution who boasted about offering mortgages to his clients at just (sic) Euribor +0.33. There are cheaper and more expensive ones, but I am appalled by the remarks that are often made on this subject by the money changers or Banks; and the street hawker of usurious goods or debt consolidation schemes and easy-to-access loans in general. This particular advert claimed that these terms made it easier for young people on lower incomes to buy their own flat. It did not specify whose property it was. Every day we’re bombarded with slogans such as: «Your home sooner than you thought», «We’ve lowered the price per square metre» or «100% financing», yet there’s little mention of the fact that it takes a lifetime and a half to pay off your flat. They’ll even lend you the deposit amount for three years so you can buy off-plan. This whole jumble of bait and hellish traps is presented under the politically correct guise of the intention to «make housing accessible to our young people». It’s a case for the magistrates’ court.
But today I want to talk to you about variable-rate mortgages: Doesn’t anyone realise that the problem no Is it within the +0.33 spread? The problem lies with the Euribor itself and the looming increase in job insecurity. Just 15 years ago, the interest rate stood at 10.40%. Mortgage enthusiasts around the world, do a quick mental calculation of what that would mean for your current «financial strategy»… Right, now anyone who’s still aware of this should add the 0.33 spread, or anyone who’s managed to negotiate skilfully.

We may not reach the interest rate levels of Barcelona ’92 or the Seville Expo, but who can guarantee that the Euribor won’t approach or even exceed that level over the next one and a half lifetimes?

Taking on a generational mortgage simply because the terms on offer are cheap today in terms of variable interest rates is like buying a Ferrari just because it’s a diesel and won’t use more than 10, 15 or 20 litres of diesel per 100 kilometres. For the vast majority of people in this country, buying a Ferrari is beyond their means, even if it saves them a pittance on premium petrol. But financial institutions mercilessly confuse and manipulate people, so that households on modest incomes with precarious wages please visit Ferraris who will dig their own financial grave, or who, at best, will be unable to get back on their feet financially for the rest of their lives, as soon as interest payments (or their working conditions) start to strangle them.

Therefore, demanding that the Euribor spread be a few hundredths lower strikes me as absurd when the real risk is being overlooked.

I always find myself smiling when I remember a scene from the Torrente series in which Gabino Diego, with the syringe still hanging from his vein, asks the waiter to bring him some orange juice. And then he insists it must be fresh-squeezed, for the sake of his health.

My friend is not suitable as a bank manager. But she has recovered a lot.

My friend Mafalda and her brother Guillermo, both bank workers, attended a few days ago some courses for private banking managers given by the Foundation of Private Banking and Personal Banking Managers and Advisors (Fundación de Gestores y Asesores de Banca Privada y Banca Personal).

They wanted to take these courses in order to be able to provide professional advice to their clients at the bank where they work. Their bosses had strongly recommended them to enrol in order to promote them as Personal Managers of small and medium-sized clients. If they became established in the position, they would subsequently be offered a job in the Master for Key Account Managers The Foundation also offers a course, with much more aggressive techniques to deal with the high competitiveness in attracting high-level clients.

She was so impressed by the course that the following week she was recommended that he resigned from his job because of an acrimonious conversation with the head of the bank's private banking department.

When she has finished her anxiolytic treatment she will start working full time, for the time being she only works in our family office in the afternoons. It has been good for her to be able to relax in the Fresh Family Office area and she has recovered a lot.

A few days ago I called his brother to congratulate him on his promotion. He was given a diploma and a commemorative video of the postgraduate course.


Guillermo asked me for an appointment and he seemed very agitated. I think he likes me.

Crisis? What Crisis?

“Things are really bad”. This is the refrain we are hearing every day in every corner of society, across all sectors and economic strata, with the exception of the very highest. Moreover, what began as a murmur amongst the most pessimistic and/or alarmist voices has gradually in crescendo until it has become a rallying cry today. Soon to be heart-wrenching.
Some are predicting a serious economic crisis that could lead to a financial collapse. There are those who talk about the future “corralito” Spanish. Those not-so-distant and recurring times when Argentinians would pack their savings into suitcases, briefcases and rucksacks to cross the Río de la Plata (the ‘charco’) in search of safe investments in their nearest paradise: Uruguay. That crisis in the neighbouring giant gave a further boost to the already luxurious coastal town of Punta del Este, a few kilometres from Montevideo – the Marbella of wealthy Argentines and Brazilians. Time will tell, but I sincerely believe we are a long way from that scenario.
Before the economic and financial system suffers structural damage that threatens its very survival, there is a long and painful road ahead: society still has plenty of room to become even poorer. By this we mean that we are still a long way from reaching the levels of “social suffering” seen in those South American countries. Although, unfortunately, the gap is narrowing.
The economic prosperity we enjoyed until very recently is still fresh in our minds: holidays, investment, consumer spending in general and optimism. The term was coined a person earning a thousand as the epitome of the final link in our financial system. Below this lies marginal and minority poverty – though that does not make it any more acceptable. But in recent times – in recent months, I would say – the situation has been deteriorating at a dizzying pace. Pessimism has replaced joy; what little consumption remains is more compulsive than rational. The banks’ encouragement of consumption and the consolidation of loans in times like these strikes me as even more sickening. The people on a thousand-euro monthly salary are starting to be the envy of quite a few people. Just a few months ago, people were still debating whether or not there was a property crisis, or whether it was simply a deceleration in the sector’s growth. Today it is the voice of the people and tomorrow, perhaps, history. Something is changing for most people, and quickly too.
The anchoring effect which applies lucidly Fernan2 The focus on markets and property in his post also misleads us psychologically when it comes to analysing the current situation and, above all, the economic development of our society. Our psychological attachment to the prosperity of recent times distorts our perception of reality. Yet, on the whole, the financial situation of the majority of the population is getting worse day by day.
Those who analyse the situation with a degree of discernment and speak of playpens, they thus attribute the difficulties to the financial system. According to them, the economy could suffer severely from the excesses of the property bubble, the banks could be overwhelmed and the state rendered incapable. No, gentlemen, the first on the list and those most likely to suffer in this scenario are ordinary citizens. In other words, the majority. Perhaps their attachment to the former welfare state is misleading them, but before the financial system begins to falter, the personal finances of ordinary citizens will deteriorate as far as necessary.
Fortunately, there is still a long way to go before our society reaches the level of social unrest seen in South America. Here, the rich can still drive around in Mercedes and BMWs, and even Porsches and Ferraris. In Brazil, no millionaire dares to be seen in anything more ostentatious than a Passat; you often see mid-range cars with a chauffeur and the passenger seat occupied. Express kidnappings are still in their infancy in Spain, and detached houses are still inhabited without having to be part of gated estates, with access barriers and armed security guards in their guardhouses in the darkest style Checkpoint Charlie, as is the case in most of the southern hemisphere.
It is true that we are beginning to hear about these ‘express’ kidnappings in our society, that burglaries – both violent and non-violent – in detached houses are now commonplace, and that crime in general is on the rise. However, these are not public order problems caused by a relaxation of security measures, but rather by the increase in need of certain sections of the population. Immigration does not help in this regard either, and the ‘state of discontent’ from which they fled seems to be growing ever closer to our now-longed-for ‘welfare state’.
But “don’t worry”, the blood of everyone It won’t reach the river. Our financial system is not in mortal danger as long as there is scope for further social deprivation. Unfortunately, that’s just the way it is. But the anchor effect In good times, it helps us look the other way. As he said, Supertramp in 1975: Crisis? What Crisis?

Security Notice

We have been made aware of phishing and spoofing attempts involving fraudulent email addresses and domains that closely resemble our official company communications. These unauthorized communications are not sent by our company and may falsely impersonate our employees or representatives.

Our company is not responsible for communications, requests, or transactions originating from fraudulent or unauthorized email addresses or domains. Please verify that all communications originate from our official email domain before responding or sharing any information.

If you receive a suspicious email claiming to be from our company, please do not respond, click any links, or provide any information. Contact us directly using the contact information published on this website to verify its authenticity.